Final Oral Defense of Conanan, Raul Jarod
Online
 27 Jun 2026 10:00 am
-
27 Jun 2026 11:30 am
The Department of Information Systems and Computer Science
invites you to the Final Oral Defense
of
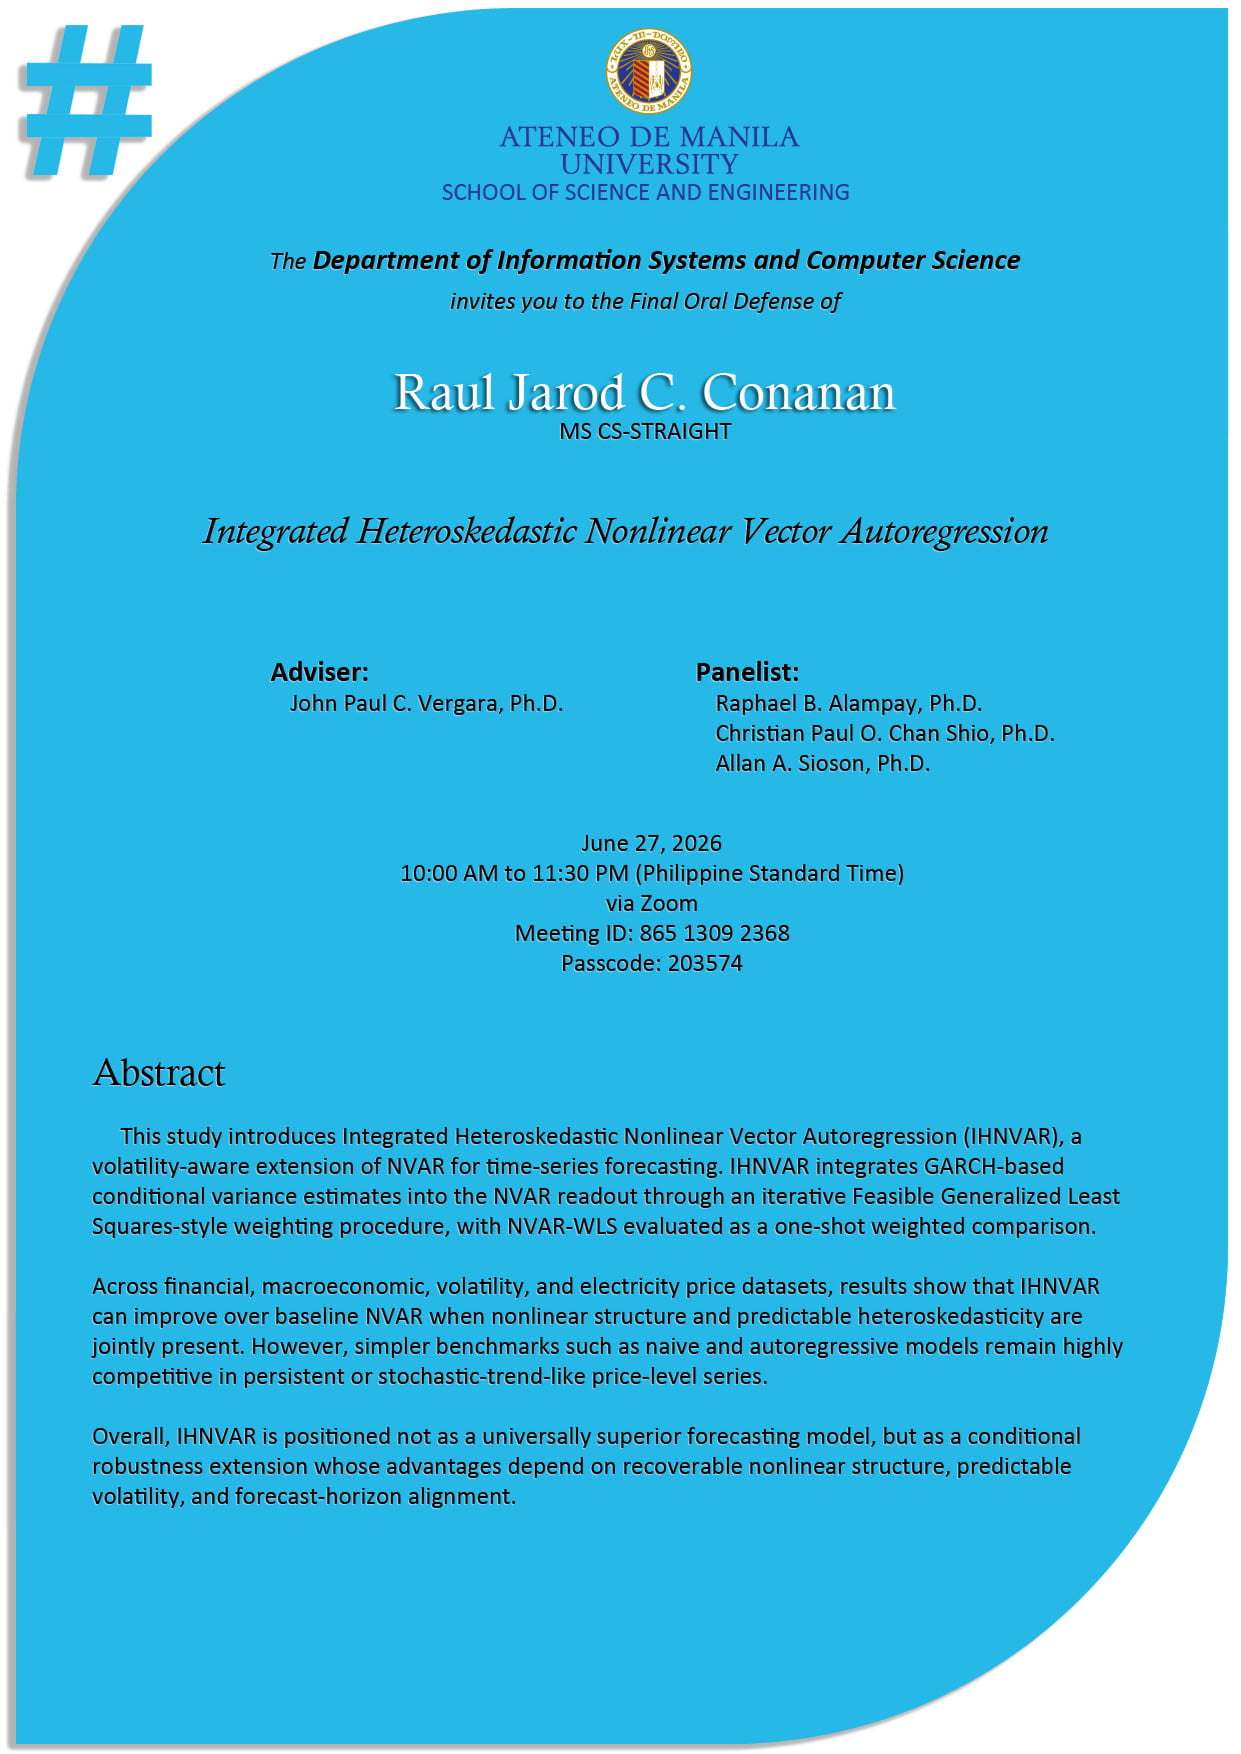
Raul Jarod C. Conanan
MS CS-STRAIGHT
Integrated Heteroskedastic Nonlinear Vector Autoregression
Adviser
John Paul C. Vergara, Ph.D.
Panelists
- Raphael B. Alampay, Ph.D.
- Christian Paul O. Chan Shio, Ph.D.
- Allan A. Sioson, Ph.D.
June 27, 2026, 10:00 AM to 11:30 AM (Philippine Standard Time)
Via Zoom, Meeting ID: 865 1309 2368, Passcode: 203574
Abstract
This study introduces Integrated Heteroskedastic Nonlinear Vector Autoregression (IHNVAR), a volatility-aware extension of NVAR for time-series forecasting. IHNVAR integrates GARCH-based conditional variance estimates into the NVAR readout through an iterative Feasible Generalized Least Squares-style weighting procedure, with NVAR-WLS evaluated as a one-shot weighted comparison.
Across financial, macroeconomic, volatility, and electricity price datasets, results show that IHNVAR can improve over baseline NVAR when nonlinear structure and predictable heteroskedasticity are jointly present. However, simpler benchmarks such as naive and autoregressive models remain highly competitive in persistent or stochastic-trend-like price-level series.
Overall, IHNVAR is positioned not as a universally superior forecasting model, but as a conditional robustness extension whose advantages depend on recoverable nonlinear structure, predictable volatility, and forecast-horizon alignment.
Latest Events
Lecture / Talk / Discussion
Navigating AOM Submissions: The Annual Meeting and Journals
Mon, 23 Nov 2026
Thesis / Dissertation Defense
Proposal Defense of Emrick James A. Panganiban, Christian Rey S. Paraan, and Ada Jemina T. Plata
Wed, 25 Nov 2026
Lecture / Talk / Discussion
An Indictment of Spanish Colonialism: The French Translation of Jose Rizal’s First Novel (1899)
Wed, 25 Nov 2026
Thesis / Dissertation Defense
Proposal Defense of Deanne Gabrielle D. Algenio, Vince Dexter Y. Ang, and Josh Tiffton M. Bolipata
Thu, 26 Nov 2026